
Nomura raised the target price for Bharat Electronics to Rs 520, maintaining a buy rating. The firm got Rs 75 billion in orders during 1HFY27. Management said its focus on indigenisation was likely to make margins sustainable. Strong order momentum is expected to continue as the company eyes many defence projects.
Market Mastery
Webinar by Vishal Malkan
Find the weak links
in your portfolio by Vishal Malkan
Nomura has maintained its 'Buy' rating on Bharat Electronics (BEL) and raised its target price to Rs 520 from Rs 500, citing the company's strong order pipeline across multiple defence segments and robust operational performance in the first half of FY27.
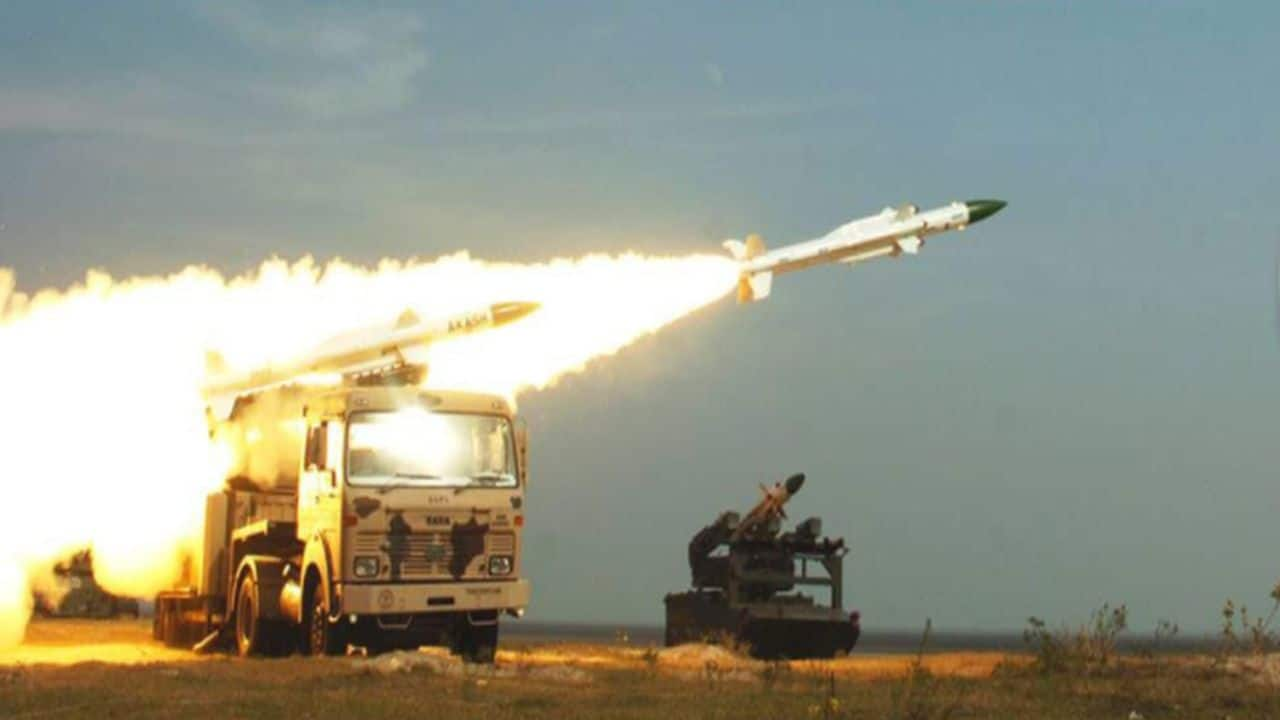
BEL received order inflows of Rs 75 billion in 1HFY27, while management retained its guidance of securing at least Rs 550 billion in orders during FY27. The Rs 300 billion QRSAM contract is awaiting Cabinet Committee on Security (CCS) clearance, which the company expects at the next meeting.
Nomura highlighted a sizeable opportunity pipeline for the second half of FY27. This includes weapons, sensors and navigation systems for next-generation corvettes, with the estimated opportunity revised upwards to around Rs 200 billion from Rs 80-100 billion earlier. Other opportunities include Shatrughat-Samaghat electronic warfare platforms worth Rs 90 billion, HAMMER precision-guided munitions worth Rs 25 billion and Shakti phase IV worth Rs 20 billion.
The brokerage believes BEL is entering a phase of substantial contract acquisitions, with order momentum expected to remain strong beyond FY27. Its assessment is supported by annual base order inflows of Rs 160-200 billion from maintenance contract renewals and recurring subsystem orders, as well as opportunities linked to major naval and defence programmes.
These include the P75(I) submarine project, next-generation destroyers and P17B frigates, along with Project KUSHA, the Advanced Medium Combat Aircraft (AMCA) programme, drone-based ELINT and anti-drone platforms, and expansion of the Integrated Air Command Control System infrastructure.
BEL reported a second-quarter FY27 profit after tax of Rs 15.4 billion, beating Nomura's estimate by 11% and consensus estimates by 15%. Management retained its FY27 revenue growth guidance of 15% or higher and EBITDA margin guidance of 28% or higher, against Nomura's estimates of 17.4% and 28.6%, respectively.
Management said its focus on indigenisation was likely to make margins sustainable and provide a strong hedge against material cost escalations. It also said it was not alarmed by the QRSAM order delay, adding that execution could be faster than user expectations once the order was received.
Nomura expects BEL's order book to nearly double over FY26-29 to Rs 1.36 trillion and models an EPS CAGR of around 17% over the period. The stock trades at 33 times and 29 times its FY28 and FY29 estimated earnings, respectively. The brokerage has raised its target price to Rs 520, based on an unchanged target P/E multiple of 42 times, as it rolls forward its valuation to September 2028.