
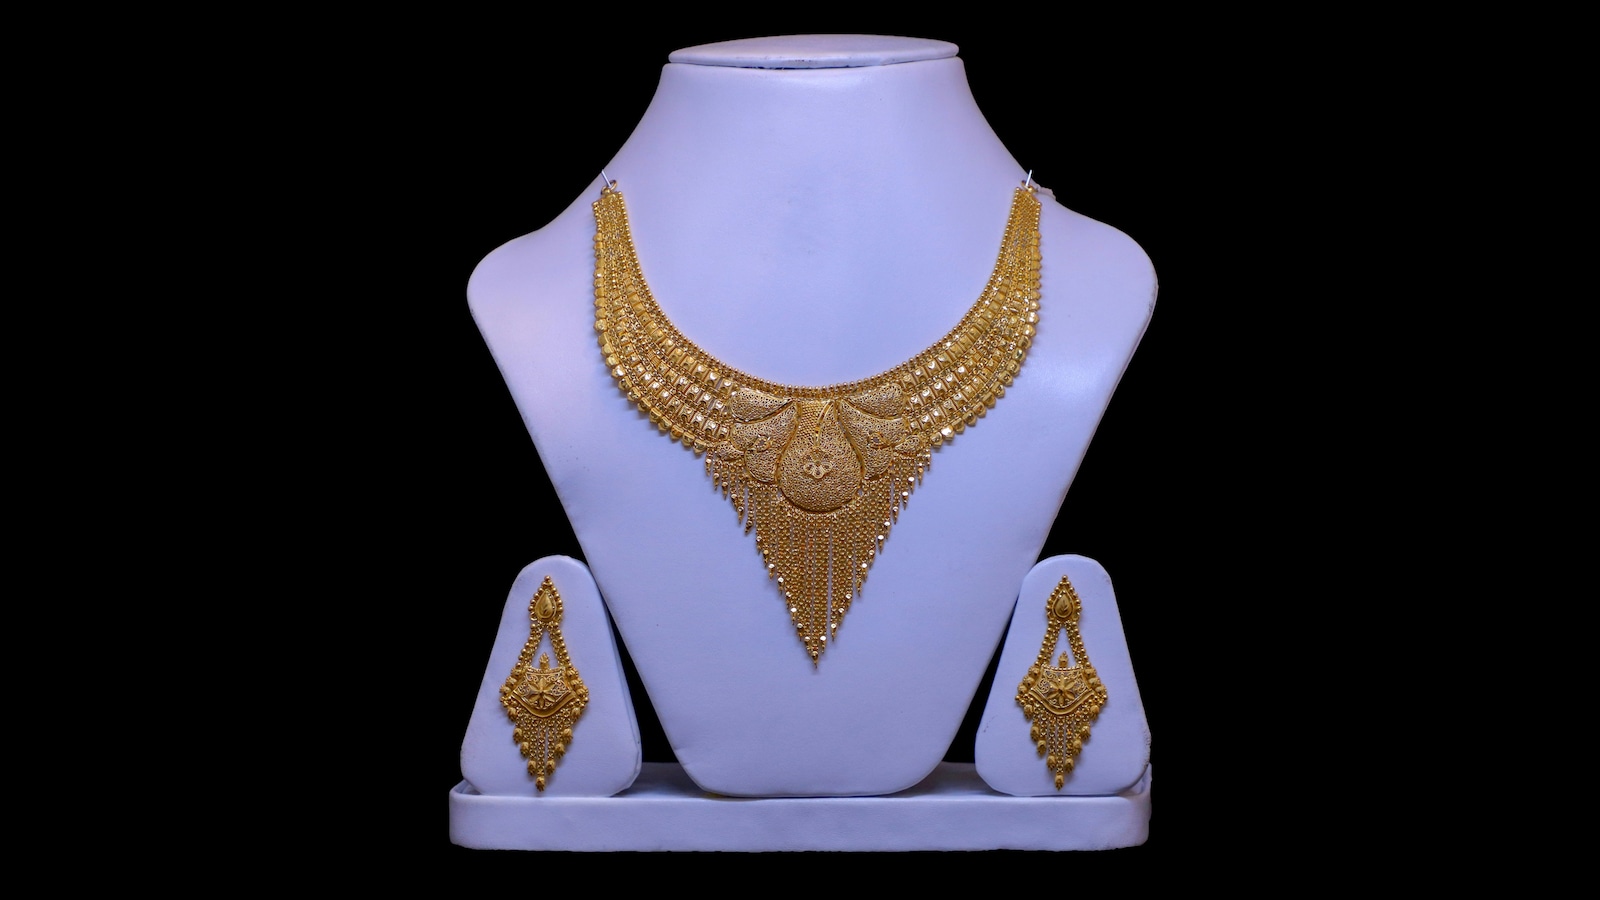
Gold jewellery received as a gift from parents is tax-free when you get it. However, selling that gold later can attract capital gains tax on the profit made. The tax depends on the original cost and how long you held the jewellery. Keep gift proofs handy to avoid future tax issues.
Gold jewellery received from parents as a wedding gift may not attract tax at the time of receipt, but selling it years later can have tax implications. If you sell the jewellery to meet expenses such as home repairs or other financial needs, the profit may be subject to capital gains tax. The tax liability depends on how long the gold was held and its original cost of acquisition.
Receiving Gold From Parents Is Usually Tax-Free
Under India's income tax rules, gold jewellery received as a gift from your parents is generally not taxable when you receive it. Parents fall under the category of specified relatives, and gifts from them are exempt from tax, regardless of the value.
So, whether your mother gives you a gold necklace on your wedding day or your father passes down family jewellery, you generally do not have to pay income tax simply for receiving it.
However, keeping some proof of the gift, such as photographs, bills or a written gift declaration, can be helpful if questions arise later.
What Happens When You Sell the Gold?
This is where things get different because while the receipt of gold could be tax-exempt, the sale of the gold can result in capital gains tax liability.
The capital gains tax is charged on the profit made and not on the total receipt from the jeweller. In most cases, the cost of acquisition of the asset would include the initial cost incurred by your parents. There are special provisions in determining the cost and holding period of inherited or gifted property.
For example, if your parents had purchased jewellery several years back and you sell it now at a higher price, the difference may be taxed as capital gains after deducting the applicable cost and expenses. The applicable tax treatment will depend on when the gold was acquired and disposed of.