
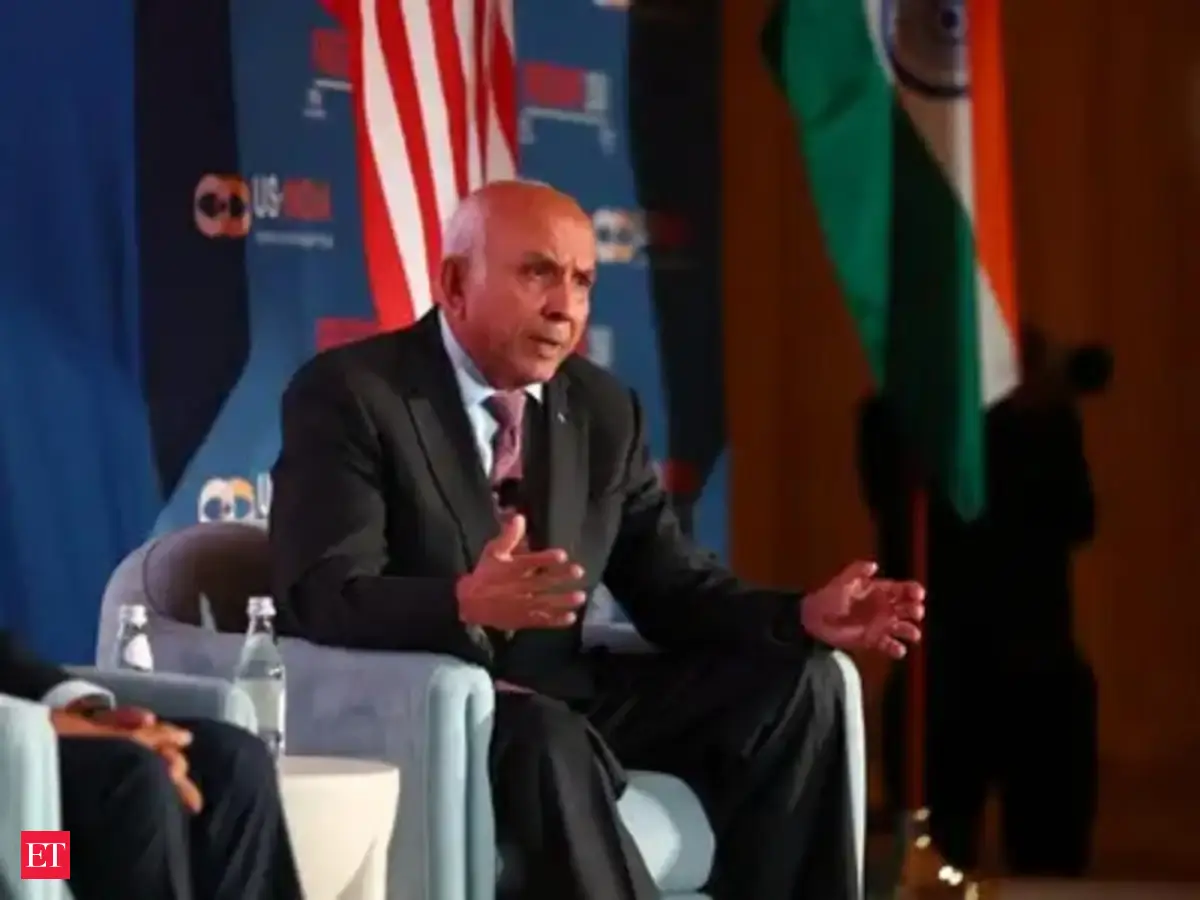
Prem Watsa is betting big on gold mining companies despite falling prices. His firm, Fairfax Financial, holds large stakes in Equinox Gold and Eldorado Gold, together worth over $1.17 billion. While bullion prices fell 8% in the week to November 20, Watsa continues to use these miners for his portfolio.
Synopsis
Prem Watsa has made significant investments in gold mining companies Equinox Gold and Eldorado Gold. His portfolio reflects a sizable commitment amid declining gold prices affecting the market. Despite unfavorable conditions regarding gold, UBS and Morgan Stanley foresee a recovery towards $5,000 per ounce by 2027. Central bank purchases and geopolitical factors are expected to sustain long-term demand for gold.
Gold is having one of its worst stretches in months, but Prem Watsa, the Canadian billionaire investor often called Canada's Warren Buffett due to his value investing style, appears to be doubling down on the precious metal through two large mining investments.
Watsa's portfolio at the end of the third quarter of 2026 held 24.51% in Equinox Gold and 19.89% in Eldorado Gold, giving the two miners a combined weight of 44.4%, as per GuruFocus, a research platform and financial data provider.
The positioning comes as bullion has fallen sharply from its January record, with prices dropping about 8% in the week to November 20 alone.
Watsa's gold bet is hard to miss
Live Events
Fairfax Financial Holdings, the insurance and investment company led by Watsa, reported 34 stock holdings worth approximately $2.65 billion in its latest third-quarter filing, according to GuruFocus. Equinox Gold was the biggest position at $649 million, while Eldorado Gold was valued at roughly $527 million. Together, the investments accounted for more than $1.17 billion of the reported US equity portfolio.
The two positions were not identical in their quarterly activity. Equinox was a new holding, with Fairfax reporting 58.4 million shares. Eldorado, meanwhile, was already in the portfolio and its position was unchanged in share terms from the previous quarter. Fairfax also exited its position in Orla Mining during the quarter, suggesting a reshuffling of its exposure within the gold-mining industry rather than a straightforward expansion across several producers.
The portfolio filing, however, does not disclose Watsa's reasoning for selecting these companies or establish a specific gold-price target behind the investments.
Notably, a 13F reports Fairfax's US-listed equity holdings, not its entire investment portfolio. It also does not establish that Watsa personally made every investment decision, but the size of the two positions makes gold mining a defining feature of the disclosed portfolio.
Why gold miners rather than bullion?
Buying mining companies is a more leveraged way to invest in gold than holding the metal itself. Miners sell gold at prevailing market prices but incur operating costs related to labour, energy, equipment and processing. When gold prices rise faster than these costs, their profit margins can expand disproportionately.
The reverse is equally important. A sustained decline in bullion can squeeze margins and weigh heavily on mining shares. Production interruptions, cost overruns and project delays add risks that investors in physical gold do not face.
Gold's sudden losing streak
The near-term backdrop is decidedly uncomfortable for gold investors. According to Reuters, spot gold fell to $3,585.92 an ounce on November 20 after touching $3,513.54, its lowest level since September 2025. Bullion was down approximately 8% for the week, its steepest weekly decline in eight months.
The selloff has been fuelled by expectations of tighter US monetary policy. Federal Reserve officials have warned that persistent inflation could warrant another interest-rate increase. Markets were pricing in a 99% probability of a 25-basis-point hike in December, according to CME's FedWatch tool cited by Reuters.
Higher Treasury yields make interest-bearing assets more attractive relative to gold, which generates no income. A stronger dollar also makes bullion more expensive for buyers using other currencies. Reuters reported that the broader technology stock selloff triggered forced liquidation of some gold positions as investors raised cash to cover losses elsewhere. The correction has not entirely discouraged physical buyers. Reuters reported that demand for gold picked up in India and China during the week's decline, with bargain hunters taking advantage of lower prices.
UBS sees gold reaching $5,000 by the end of 2027
UBS expects gold to recover from its recent decline and reach $5,000 an ounce by December 2027. In its November 18 outlook, the Swiss bank forecasts bullion at $4,600 by June 2027 before climbing further towards $5,000 by year-end.
The bank's bullish case rests on continued central-bank purchases, robust Chinese demand and concerns about rising government debt. It also points to relatively resilient gold ETF holdings as a source of support. These factors could offset the near-term pressure from elevated US real interest rates and a firm dollar, both of which make non-yielding gold less attractive.
UBS acknowledges that bullion could fall further in the near term if markets continue pricing in tighter Federal Reserve policy. However, it expects longer-term investors to step in around those levels. If expectations of further US rate increases recede, real yields could ease and provide room for gold to recover in 2027.
The November outlook follows an October 19 UBS Chief Investment Office report which had forecast gold reaching $5,400 an ounce by September 2027. That earlier report described gold as a strategic portfolio hedge and diversifier, citing central-bank buying, reserve diversification, elevated government debt and geopolitical uncertainty. It also suggested that pullbacks towards $4,000 could offer opportunities to add exposure. The lower target in the November outlook reflects a subsequent reassessment of the price outlook, although UBS continues to favour gold as a long-term portfolio diversifier.
Morgan Stanley picks gold as its top commodity for 2027
Morgan Stanley is also maintaining a constructive outlook, although its November research makes an important distinction between gold and the broader commodity market. In its November 18 Outlook, the US investment bank downgraded commodities as an overall asset class to underweight but retained gold as its preferred commodity for the coming year.
The bank expects gold to benefit from continued purchases by central banks and inflows into gold-backed exchange-traded funds. It also argues that an easing of tensions in the Middle East could bring oil prices and interest-rate expectations lower, making gold more attractive relative to interest-bearing investments such as bonds and cash.
A separate gold analysis by Morgan Stanley commodities strategist Amy Gower, reproduced in the bank's another report this month, provides more detail on the demand picture. Drawing on an October research report, Gower said gold has shown resilience despite the September Federal Reserve rate hike, a stronger US dollar and elevated global bond yields. Morgan Stanley & Co. Research expects gold to reach $5,000 an ounce by the second quarter of 2027.
The analysis highlights central-bank purchases of 289 tonnes in the second quarter of 2026, equivalent to an annualised rate of 1,155 tonnes. China's central bank had purchased 103 tonnes during the year up to the reporting period, its highest level since 2023. Chinese gold imports also reached 1,100 tonnes through August, the highest annualised pace since at least 2017. Morgan Stanley sees these purchases as evidence that structural demand is helping offset the pressure from higher interest rates.
A long-term argument against a difficult market
The bullish forecasts do not mean gold is about to reverse its decline. Higher interest rates and a stronger dollar remain immediate obstacles, while central-bank buying and investor demand can fluctuate.
But the underlying argument from UBS and Morgan Stanley is that gold's appeal extends beyond short-term inflation hedging. Concerns about government debt, currency diversification and geopolitical uncertainty could sustain demand over a longer period.
That might provide some context for Fairfax's substantial mining exposure, although it does not prove that these are the precise considerations behind Watsa's investment decisions. For now, his portfolio offers a striking contrast with the prevailing market weakness. While gold investors are retreating, a large part of Fairfax's disclosed US stock portfolio is tied to two gold producers.