
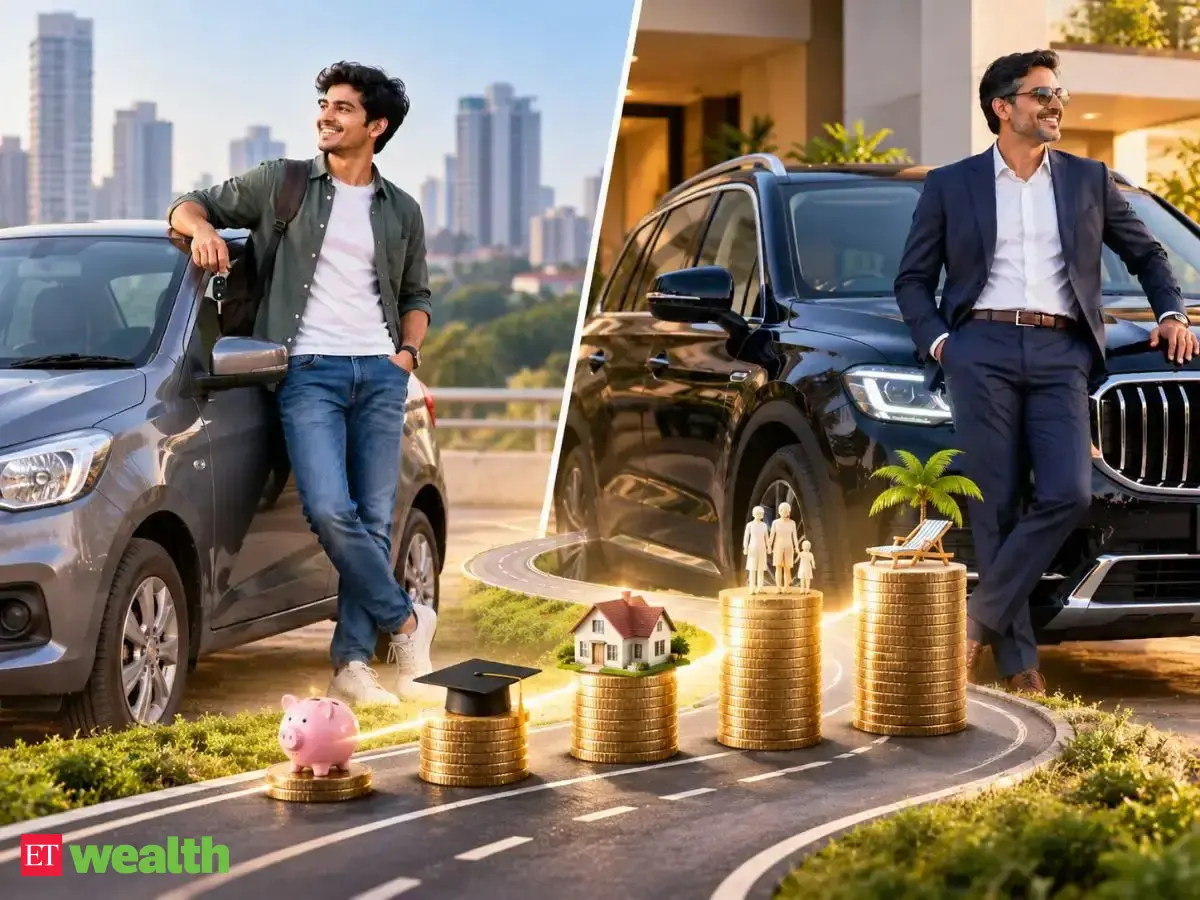
Buying your first car at 25 versus a luxury car at 40 requires careful financial planning. Experts said, "The goal is to enjoy your car without putting your financial future in the back seat." You should choose a vehicle based on your current salary rather than future income expectations.
Buying your first car at 25 vs a luxury car at 40: How your car budget should change with age and income
1/9
Your dream car could cost you more than you think
At 25, buying your first car can feel like a sign that your career is finally taking off. By 40, you might be dreaming of a luxury upgrade. But the financial decision is bigger than choosing between two cars. The money you spend on a vehicle is money you cannot use elsewhere. The goal is to enjoy your car without putting your financial future in the back seat.
2/9
At 25, your first car should fit your current salary
Your career may be on the rise, but future salary hikes are not guaranteed. Choose a car based on what you earn today, not what you hope to earn five years from now. A reliable hatchback, compact SUV or well-maintained used car can meet your needs without leaving you short of money for rent, emergencies, investments and other priorities.
3/9
A ₹10 lakh car vs a ₹40 lakh luxury car: See the EMI difference
Consider two illustrative car loans, each with a five-year tenure and an assumed interest rate of 9% per year.
Car A: ₹10 lakh car
Down payment: ₹2 lakh
Loan amount: ₹8 lakh
Estimated EMI: ₹16,600 a month
Total interest over five years: approximately ₹2 lakh
Car B: ₹40 lakh luxury car
Down payment: ₹8 lakh
Loan amount: ₹32 lakh
Estimated EMI: ₹66,400 a month
Total interest over five years: approximately ₹7.8 lakh
The luxury car requires ₹6 lakh more upfront and around ₹49,800 more in monthly EMI. These figures exclude insurance, fuel, maintenance, taxes and other ownership costs. Actual loan terms will vary.
4/9
The EMI is only the beginning of your car expenses
Your monthly repayment does not tell you the full cost of owning a car. You also need to pay for fuel, insurance, servicing, tyres, parking and unexpected repairs. Luxury cars can carry higher insurance and maintenance bills, although costs vary by model. Before buying, calculate the total ownership cost and check how much money you will have left each month.
5/9
By 30, a bigger salary may come with bigger responsibilities
Your income may rise as your career progresses, but so can your expenses. A home loan, children's education, support for parents or other family commitments can absorb much of your additional income. Before upgrading your car, look at your complete household budget. A bigger paycheque does not automatically mean you can comfortably afford a bigger EMI.
6/9
At 40, should you finally buy that luxury car?
A luxury car can be a reasonable reward for years of hard work, especially if you have built savings, reduced debt and established a strong investment habit. Comfort, safety features and driving experience may matter more to you now. But age alone is not a reason to upgrade. Buy the car when your finances support the purchase, not because you feel you have reached the age when you should own one.
7/9
Will your luxury car delay retirement or other goals?
Imagine committing an additional ₹49,800 every month to a luxury-car EMI instead of keeping that money available for investments or other priorities. Over five years, those payments total nearly ₹30 lakh. That does not mean investing the entire amount would guarantee a particular return, but it shows the scale of the financial commitment. Consider whether the upgrade is worth what you may have to postpone.
8/9
Three financial checks before you buy or upgrade
1. Protect your emergency fund. Do not empty your savings to make a larger down payment. Keep enough accessible money for unexpected expenses and income disruptions.
2. Calculate the complete monthly cost. Include the EMI, fuel, insurance, servicing, parking and other recurring expenses.
3. Keep your long-term goals on track. Make sure retirement contributions, essential family expenses and other planned investments remain affordable after buying the car.
If the purchase compromises these priorities, consider a less expensive model or wait until your finances improve.
9/9
The smartest car budget changes with your life
At 25, prioritise reliable transport and the freedom to build your savings. At 40, consider a luxury upgrade if your income, investments and financial commitments allow it. There is no universal age or salary at which a luxury car becomes the right choice. Your best car is one you can enjoy without sacrificing your financial security.