
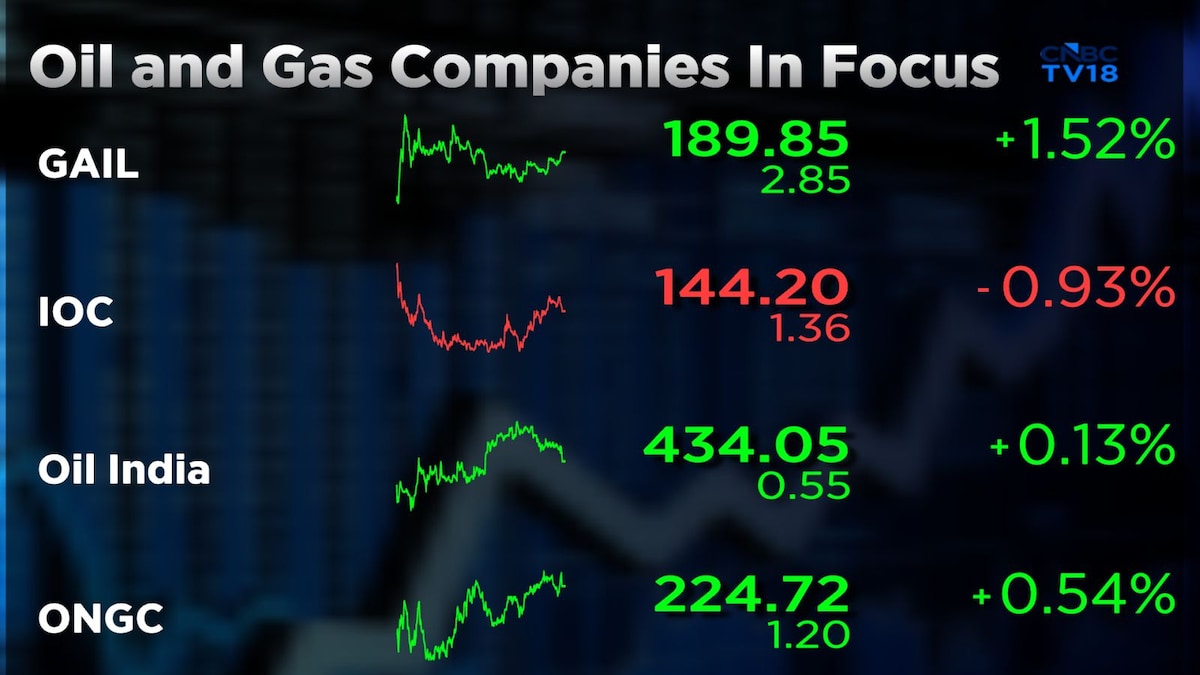
The government’s decision to allow longer production sharing contract extensions could drive fresh upstream investments. Probal Sen from ICICI Securities said, "Now you can basically get your extension in much longer blocks of around 30 years at a time." The brokerage remains positive on Oil India and GAIL shares.
The government's decision to allow longer production sharing contract (PSC) extensions could encourage fresh investments in upstream oil and gas fields by giving operators greater visibility over project life, according to ICICI Securities. The brokerage also remains positive on Oil India and GAIL.
The government's decision to relax production sharing contract (PSC) extension norms is expected to improve long-term investment visibility for upstream oil and gas companies, according to Probal Sen, Senior Research Analyst covering the Indian Oil & Gas and Agrichem sectors at ICICI Securities.
Sen said the revised framework allows operators to secure contract extensions for much longer periods, enabling them to plan investments aimed at sustaining or increasing production. While the benefits may take time to materialise, he believes the policy is a positive step for companies operating PSC assets. He also maintained a positive outlook on Oil India and GAIL, while saying upstream earnings should remain supported by crude prices.
Explaining the policy, Sen said, "Now you can basically get your extension in much longer blocks of around 30 years at a time." He added that this gives operators confidence to invest in technologies such as enhanced oil recovery.
According to Sen, companies operating PSC assets, including Cairn's Rajasthan and Ravva fields, stand to benefit the most from the change. He added that Oil and Natural Gas Corporation (ONGC) and Oil India could also gain indirectly through their joint venture interests in such assets. Smaller exploration companies with PSC-operated fields may also benefit by extending the productive life of their assets.
However, Sen noted that the policy comes with a higher government profit-sharing component, meaning project economics will continue to be an important factor before companies commit fresh investments.
On crude oil prices, Sen said ICICI Securities continues to expect realisations for ONGC and Oil India to remain in the $85-$90 per barrel range despite recent weakness in benchmark prices.
"Our base case even for H2 remains in the $85 to $90 per barrel range," he said, adding that the geopolitical risk premium continues to support oil prices above historical levels.
Based on this outlook, Sen expects upstream companies to report healthy earnings, supported by stable crude prices and improving production. He said Oil India remains the brokerage's preferred upstream pick, citing operational improvements and strong refining performance at Numaligarh Refinery.
Within the gas space, Sen said city gas distributors could continue to face margin pressure as they prioritise volume growth. In contrast, gas transmission companies are better placed.
"Among the two, based on valuations and visibility on earnings, GAIL remains the preferred pick," he said.
On oil marketing companies (OMCs), Sen said the investment case is more gradual. He prefers Indian Oil Corporation (IOCL) because stronger refining margins could offset pressure from retail fuel marketing and inventory losses.
He also expects refining margins to remain healthy in the near term, noting that diesel and aviation turbine fuel (ATF) cracks continue to support profitability despite some moderation in gasoline spreads.