
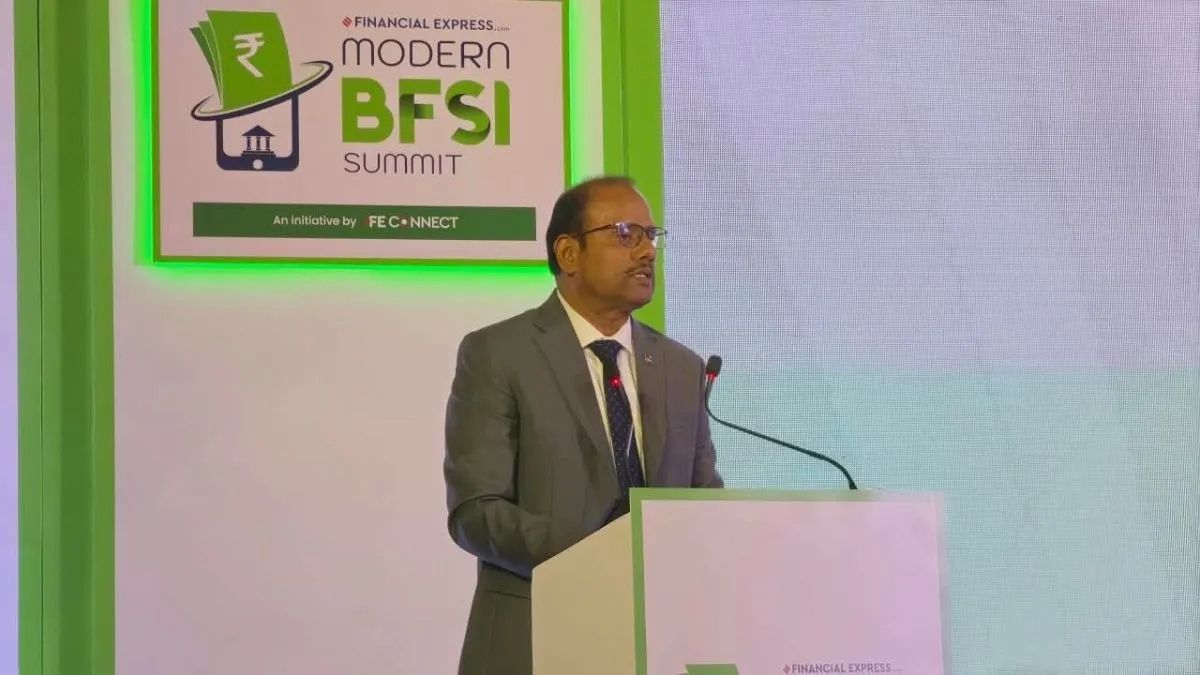
RBI Deputy Governor Swaminathan said institutions must ensure oversight keeps pace with their growth. At the Financial Express Modern BFSI Summit in Mumbai, he noted, “Oversight and controls should also grow, commensurate with or keep pace with the growth of the organisation.” He added that building trust remains essential for sustainability.
Speaking at the Financial Express Modern BFSI Summit in Mumbai, Swaminathan said institutions must treat stakeholders, particularly customers, fairly and earn their trust every day to build sustainable balance sheets.
“Oversight and controls should also grow, commensurate with or keep pace with the growth of the organisation. Then you are building a model that is sustainable,” he said.
Growth, he emphasised, should not be measured merely by its pace, scale or size, but also by the strength of the controls underpinning it.
Swaminathan said the Indian financial system was entering its next phase from a position of strength, supported by improved asset quality and comfortable capital buffers. The challenge, however, was to preserve these strengths as the system expanded, became more technology-intensive and increasingly interconnected.
He outlined three priorities for financial institutions. First, as institutions pursue growth and reduce friction, controls must evolve alongside business processes. Second, trust must be treated as an asset requiring continuous investment. Third, resilience must be measured not merely by the ability to withstand disruptions, but also by how quickly institutions can detect problems, take decisions and recover.
He said customer trust was tested every day through the sale of financial products, the handling of customer data and the resolution of grievances.
The deputy governor also stressed the importance of making financial products and services affordable, while responding to a question on the draft insurance guidelines proposing tighter commission norms.
He emphasized that achieving the vision of universal access to insurance, investments, social security and pensions under Viksit Bharat 2047 would require financial institutions to bring down the cost of delivering these products and services.
“All products are made fairly accessible, but are they affordable as well? If not, then they will reach only a small market and leave out a large market,” Swaminathan said.
He said affordability was an important consideration behind the proposed guidelines. The Insurance Regulatory and Development Authority of India (IRDAI) would examine the feedback received from stakeholders before taking a final decision.
Asked whether tighter commission norms could hurt banks’ fee income, Swaminathan said the loss of one revenue stream would not threaten the industry, as banks would find alternative sources of income.