
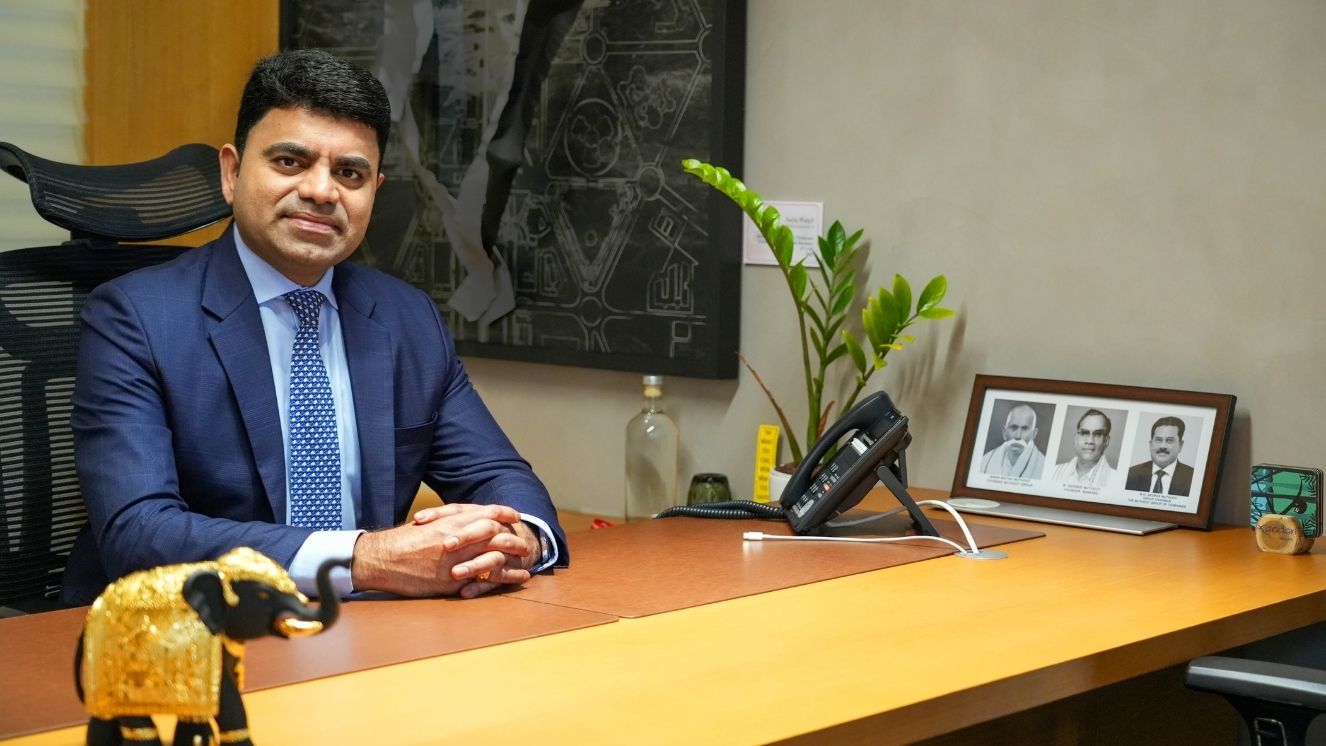
Muthoot Finance MD said gold loan fundamentals remain strong as the company raised its full-year growth guidance to 25 percent. The firm opened 262 branches this year to boost financial inclusion. While Stage-2 and Stage-3 assets increased, the MD said this reflects new RBI regulations rather than actual portfolio stress.
What are your key priorities as the new MD?
Market expansion, for sure. As a group, we opened 336 branches, of which Muthoot Finance alone accounted for more than 262. We will probably open a similar number in the future because India has almost 35,000 tonnes of gold. There is a huge opportunity to bring more people into financial inclusion through our geographical expansion. Improving per-branch productivity is another priority. We have already scaled up our average per-branch productivity to ₹34 crore. New customer acquisition also remains a key focus area. This year alone, gold loan disbursements stood at ₹20,238 crore to around 9.93 lakh customers. The number of active customers has also increased to 69 lakh from 64 lakh.
You have raised your full-year gold loan growth guidance. What gives you the confidence to do so?
At the start of the year, we had given guidance of around 15%, but we achieved that in the first six months itself. Obviously, we see more room to grow, and there is also an expectation of what the organisation can deliver over the next six months. We took a calibrated call to increase our growth guidance by another 10 percentage points, taking it to around 25% for the full financial year. The traction we have seen in the first two quarters and the way we have grown, despite all the concerns around challenges and competition, have given us confidence. Considering our performance in the first six months, we believe we will be able to scale up growth further in the second half of the year.
Stage-2 and Stage-3 assets have seen a sharp increase. Is this indicative of stress in the gold loan portfolio?
On April 1, the new RBI regulations came into effect. Shorter-tenure loans and interest-servicing schemes were introduced. Since these loans require monthly interest payments, any failure to pay can push them into the Stage-2 and Stage-3 categories. The majority of gold loan customers have been accustomed to bullet repayment schemes. These are typically 12-month loans, and only after 15 months do they become NPAs. Regular interest-servicing schemes did not exist in the gold loan industry earlier. So, it will take some time for customers to understand this structure, and we, as an organisation, have to educate them.
This does not signify any stress in the industry or among customers. It is just that customers are not used to this mechanism. It is a transition phase. We have 32,000 people working on the ground, and our branches are located close to customers. We will do our best to educate them while simultaneously managing the transition and the higher levels of Stage-2 and Stage-3 assets. I personally do not see any risk to the portfolio because these are highly collateralised loans. Our loan-to-value (LTV) ratio is also very low, at around 65% of the portfolio. If you look at the auctions in the last quarter, the numbers were negligible, probably around 1%. Even those are undertaken very selectively, as a last resort.
Some NBFCs have flagged concerns about gold loans being extended to borrowers who are already delinquent on other loans. Does this pose a risk to the industry?
For newer players, if they are doing a cross-sell or something similar within their portfolio, there is a borrower-wise classification. So, if one loan turns into an NPA, the entire book turns into an NPA. For them, it might be a bit more challenging. Gold lending is a very operationally intensive business that requires considerable expertise in gold valuation, secure storage, regular audits, fraud prevention, auction management and operational controls. These are areas that we have fine-tuned and strengthened over decades.
For newer players coming from outside the industry, the return on assets (ROA), growth and other metrics may look attractive. But once they enter the business, they realise that there are several operational challenges they have to deal with. We have gone through various cycles over the decades. We have seen NPA levels of almost 6%, but we have normalised them over time. So, there could be some transitional issues at present. However, over a period of time, we have usually been able to normalise these trends because there is a lot of emotional attachment to gold compared with other asset classes.