
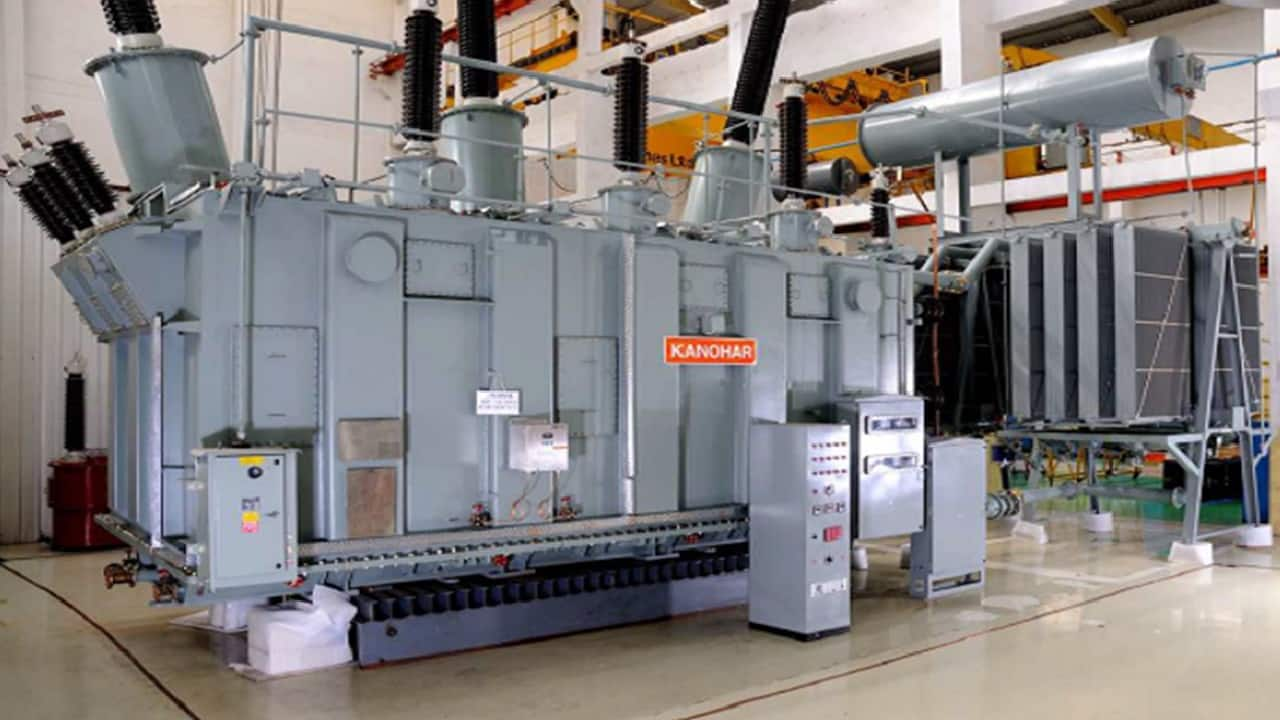
Kanohar Electricals shares rose 16 percent on October 7 after the company announced strong Q1 results. Revenue doubled to Rs 137 crore, while profit jumped 140 percent to Rs 27 crore. Whole-Time Director Abhishek Singhal said, "The improvement in profitability was driven by higher manufacturing volumes and a favourable product mix."
Kanohar Electricals shares rose 16% on October 7 a day after the newly-listed company announced strong Q1 results. According to the company's financial results, revenue from operations for the quarter ended June 30, 2026, more than doubled year-on-year to Rs 137 crore, compared with Rs 67 crore in Q1FY26. EBITDA surged 152.2% to Rs 39 crore, from Rs 15 crore a year earlier, while the EBITDA margin expanded to 28.3% from 22.8%. Profit before tax rose 134.7% year-on-year to Rs 37 crore, compared with Rs 16 crore in the year-ago quarter. Profit after tax jumped 140% to Rs 27 crore, from Rs 11 crore, with the PAT margin improving to 19.9% from 16.9%. At 12:40 pm on October 7, Kanohar Electricals shares were trading 16% higher at Rs 1,096.95 apiece. Kanohar Electricals continued the strong growth momentum from FY26 into the first quarter of FY27, with revenue doubling year-on-year, while gross margins remained healthy and EBITDA and PAT margins improved, Whole-Time Director Abhishek Singhal said. The improvement in profitability was driven by higher manufacturing volumes and a favourable product mix, led by a larger contribution from the 400 kV segment. The shift helped the company benefit from operating leverage, Singhal said. During the quarter, the company secured incremental orders worth around Rs 332.3 crore, taking its outstanding order book to Rs 2,026 crore. The order book is expected to be executed over the next 18-24 months. Kanohar Electricals is also undertaking brownfield capacity expansion at its Gangol facility, alongside investments in sustainability initiatives. The company plans to spend on these projects over the next 18 months, with the investments expected to support future growth and sustainable profitability. The company is prioritising execution of its newly secured 400 kV transformer orders and is targeting additional opportunities in the 765 kV transformer segment, where it has already established manufacturing capabilities. Singhal said certifications and pre-qualifications remain key entry barriers in the transformer industry. With operations spanning power transmission, power distribution, railways and renewable energy, Kanohar Electricals expects significant growth opportunities ahead, supported by available capacity and a steady order pipeline, Singhal said. For FY27, the company is targeting revenue of Rs 950 crore while aiming to maintain an EBITDA margin broadly in line with FY26 levels, he added. Analyst view "Q1 was very strong as revenue doubled YoY to Rs 137 Cr, EBITDA increased 152% to Rs 39 crore and PAT rose 135%. EBITDA margin expanded sharply to 28.3% vs 22.8%, helped by higher manufacturing volumes and a better product mix. More importantly, 70% of QI revenue came from 400kV transformers. This is a positive structural shift toward higher-voltage, more technically complex products rather than just volume-led growth," said Prathamesh Kadival, Research Analyst at Bonanza. Order book of Rs 2,026 crore provides strong visibility for the next 18-24 months; another Rs 332 crore of orders was added during Q1. Against FY27 revenue guidance of Rs 950 crore, visibility remains comfortable. The biggest medium-term trigger is the Gangol brownfield expansion, which should increase execution capacity as the company scales its transtormer business, he added. The 765 kV transtormer segment is the key potential re-rating trigger. Kanohar has developed the manufacturing capability but meaningful orders are yet to come. Winning 765kV orders would move the company further up the technology/value chain and can support better growth and margins, said Kadival. What is the growth story? 400/765kV order wins, order-book growth, Gangol capacity ramp up, execution toward the Rs 950 crore FY27 revenue target, and whether the unusually strong 28% QI EBITDA margin can remain broadly sustainable, he added. Overall, the Q1 results validate the growth story, while the fundamental attraction is Kanohar's transition into higher-voltage transformers backed by a Rs 2,000-crore order book and capacity expansion. The recent rally is justified by the strong print, but 765kV order conversion and margin sustainability are likely to determine the next meaningful re-rating, Kadival further said.