
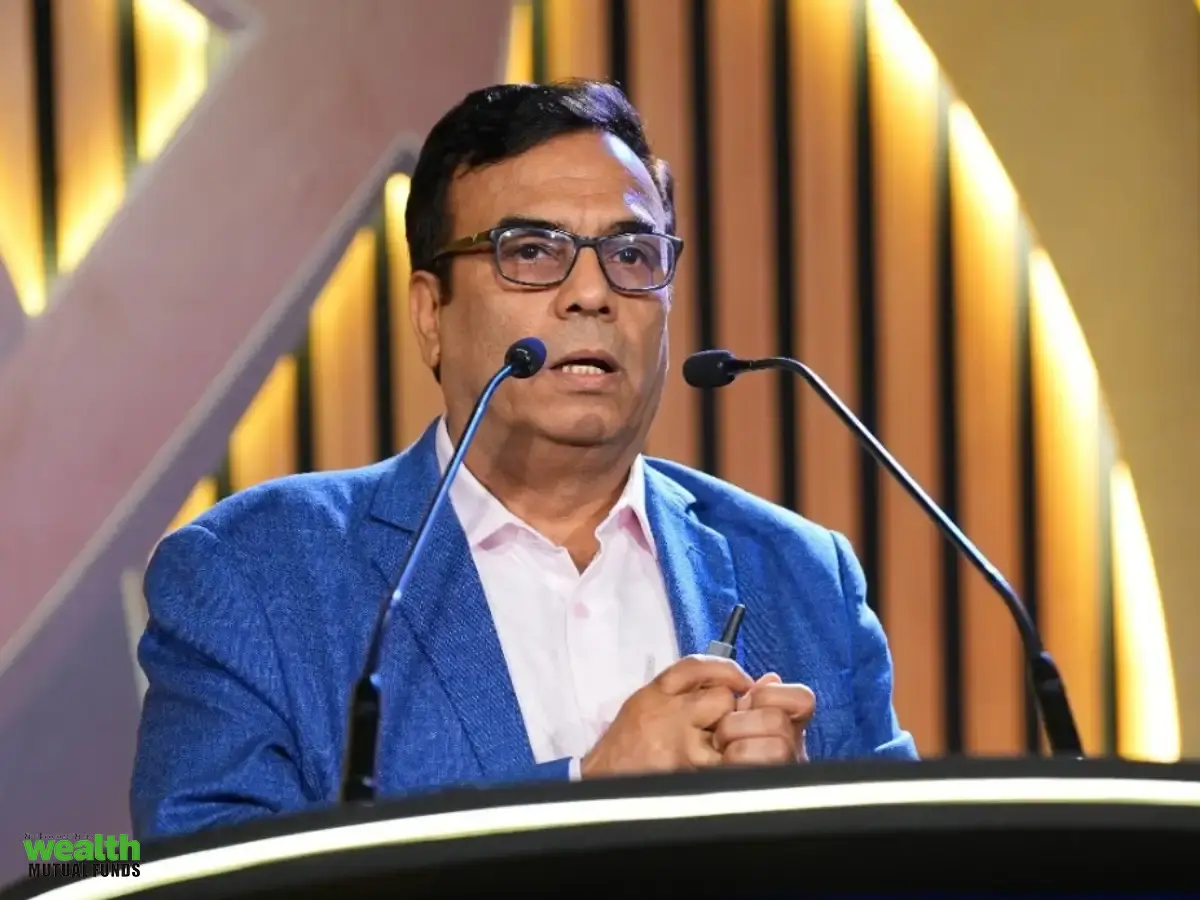
Sandeep Tandon of Quant Mutual Fund said man and machine will shape the next phase of investing at the ET Alpha Wealth Summit 2.0. He believes investors must combine human judgment with machine analytics. Static strategies are less effective now, so money management got more dynamic to find better results.
Synopsis
Quant Mutual Fund’s Sandeep Tandon says the next investment edge will come from combining human judgment with AI, machine learning and alternative data. As markets become more dynamic, investors must move beyond static strategies and focus on speed, inference and decision-making.
For investors, the challenge is no longer simply finding more information—it is determining which data matters, how quickly market conditions are changing and what action should follow. As market regimes become increasingly dynamic, Sandeep Tandon, Quant Mutual Fund, believes the next investment edge will come from combining human judgment with machine-driven analytics rather than choosing one over the other.
Speaking at the ET Alpha Wealth Summit 2.0, Tandon said the traditional approach of relying on static long-term holdings, fixed investment styles and familiar market narratives is becoming less effective in a world where opportunities and risks can migrate rapidly. For investors seeking alpha on a consistent basis, he argued, money management has to become more dynamic, outcome-driven and less constrained by conventional labels such as value, growth or market capitalisation.
Best MF to invest
Looking for the best mutual funds to invest? Here are our recommendations.
View Details »
According to Tandon, this is where the combination of human intelligence and technology becomes important. Data processing, artificial intelligence and machine learning can dramatically improve the speed at which investment professionals analyse information, but the quality of the eventual decision still depends on the human inputs and judgement used to build those systems.
Live Events
“Man and machine” therefore should not be viewed as competing forces, he said. Instead, the investment industry should focus on how effectively humans can use machines to improve productivity, processing capability and decision-making.
Tandon pointed out that the investment industry has already gone through several phases of technological change. Earlier, institutional investors could benefit from an information advantage because access to market and company data was relatively limited. With technology making information increasingly available to everyone, that advantage has diminished.
The next edge, he said, has increasingly been speed.
The ability to process thousands of data points that once required days of computing time can now be accomplished in minutes or even seconds. This has changed the economics of investment research and allows money managers to test multiple variables and scenarios much faster than before.
For investors, the implication is significant: simply having access to data is no longer enough. The ability to filter, interpret and act on that data is becoming more important.
Tandon said the industry is now moving towards what he calls a transition from an information edge and speed edge to an inference and, ultimately, a decision-making edge.
Tandon also challenged the traditional investment emphasis on valuation analytics alone. In his view, market behaviour can be influenced substantially by liquidity and investor risk appetite, particularly during periods of extreme market stress.
He cited the experience of the 2020 market disruption, arguing that looking only at fundamentals and valuations would not have fully explained the market's subsequent behaviour. Changes in global liquidity and risk appetite became critical variables in understanding the direction of markets.
His approach therefore involves changing the weight assigned to different forms of analytics depending on the market environment. During extreme conditions, liquidity and risk appetite can assume much greater importance than valuation metrics.
This has implications for investors who build portfolios around a single investment framework. A strategy that works in one market regime may not necessarily work with the same weightage when liquidity, sentiment or risk appetite changes.
Tandon said alternative data and AI are also making it possible to quantify sentiment, rather than treating it merely as a qualitative market observation. Combining sentiment and liquidity data can help create what he describes as money-flow analytics.
Another major change, according to Tandon, is the industry's move from predictive analytics towards decision analytics.
Investment professionals have traditionally been good at explaining what happened after an event. The more valuable capability, he suggested, is to use historical data, behavioural patterns and scenario analysis to improve decisions before or during an event.
Tandon said AI and machine-learning tools can accelerate this process by identifying patterns and processing large quantities of information that would otherwise be difficult for humans to analyse manually.
For investors, the value of AI therefore should not be measured simply by its ability to generate forecasts. Its greater usefulness could lie in helping investors assess scenarios, identify risks and make decisions faster when market conditions change.
Tandon said the same analytical framework can increasingly be applied to investors themselves. Instead of treating investors as a homogeneous group, asset managers can use alternative data and AI tools to better understand differences in risk appetite, investment horizon and behaviour. This could eventually allow fund houses to design and position products more closely around investor needs.
Such an approach could also help investors recognise their own behavioural biases. Tandon pointed out that investors often describe themselves as long-term and high-risk investors during market peaks, but their actual risk tolerance can change sharply when markets fall.
Capturing such behaviour over different market cycles can provide a more realistic understanding of an investor's true risk appetite. While Tandon sees considerable potential in AI, he cautioned against blindly accepting machine-generated outputs.
The rapid expansion of AI has created an environment where large volumes of information, narratives and sophisticated-looking outputs can be generated quickly. The challenge is distinguishing useful information from noise and converting it into an actionable investment decision.
For investors, this distinction is critical. AI may make analysis faster, but faster analysis does not automatically translate into better investment outcomes.
Tandon's central argument is that the quality of the human input remains crucial. The machine can process, compare and identify patterns, but investors and money managers still have to determine what questions to ask, which variables matter and how much confidence to place in the output.
Tandon also sees high-frequency analytics becoming increasingly important for investment management.
Traditional fund management has largely relied on low-frequency information such as quarterly earnings, monthly economic data and periodic company disclosures. However, market data—particularly derivatives and tick-by-tick information—is generated continuously.
For investors, this could mean that the competitive advantage of active management increasingly depends not only on identifying good companies but also on understanding how market liquidity, positioning, sentiment and risk appetite are changing in real time.
Tandon's broader investment thesis is that every technological or informational advantage eventually becomes widely available.
An information edge that was once exclusive becomes common. Technology that initially provides an advantage eventually becomes a commodity. The next edge then moves to another layer. That makes adaptability increasingly important for investment managers.
Tandon believes the industry is now moving from information and speed advantages towards decision analytics. The firms that can effectively combine human judgement, proprietary processes, alternative data and machine capabilities could have a greater ability to respond to changing market conditions.
For investors, the message is less about replacing traditional investment expertise with AI and more about understanding how the investment process itself is evolving.
In Tandon's view, the future is neither purely human nor purely machine. It is about how effectively the two can work together—and how quickly investors and money managers can adapt before yesterday's investment edge becomes tomorrow's commodity.
If you have any mutual fund queries, message ET Mutual Funds on Facebook/Twitter. We will get them answered by our panel of experts. Do share your questions at ETMFqueries@timesinternet.in along with your age, risk profile, and Twitter handle
(Catch all the Mutual Fund News, Breaking News, Budget 2024 Events and Latest News Updates on The Economic Times.)
Subscribe to The Economic Times Prime and read the ET ePaper online.
...moreless
(Catch all the Mutual Fund News, Breaking News, Budget 2024 Events and Latest News Updates on The Economic Times.)
Subscribe to The Economic Times Prime and read the ET ePaper online.
...moreless
The NBFC saga - Part 2: Line drawn in 2006 is reason for the headlines today
Airlines Q2 turbulence: Fewer passengers, rising fares and a crude shock
Britannia’s next big bet for young India lies beyond biscuits
The world is witnessing a bond rout. Why should it matter to you?
Q2 earnings season: Will it settle or add to confusion in the stock market?
The NBFC saga - Part 1: How RBI moved from protecting depositors to policing systemic risk